Three Ways Supply Chain Disruptions are Impacting the Commercial Real Estate Market
Rising demand for warehouse space, re-shoring and last-mile logistics among the biggest trends
The emergence of the coronavirus in early 2020 caused a drastic slowdown in supply chains across the globe. Labor shortages, fluctuating consumer demand, disruptions in shipping lanes, COVID-19 restrictions as well as general economic uncertainty caused major disturbances in the flow of goods. The war in Ukraine further compounded these issues by cutting off the supply of critical raw materials and ratcheting up energy costs. These disruptions have caused several challenges and opportunities for commercial real estate as the industry focuses on restoring the reliability of the global supply chain. Here are three of the most significant impacts:
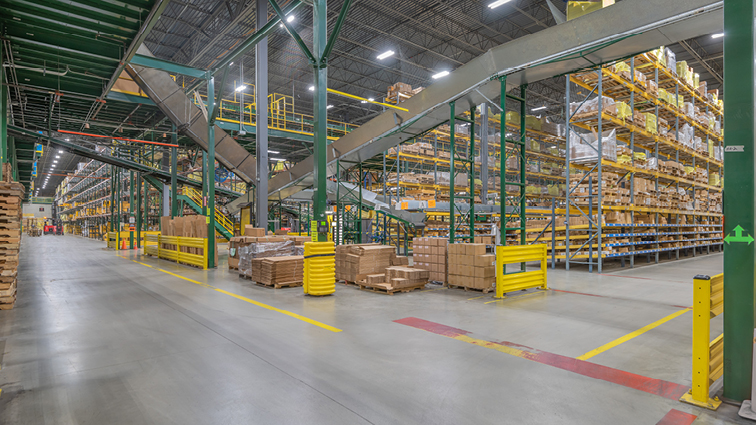
Rising demand for warehouse space
During the pandemic, many companies struggled to restock in-demand products driven by a steep increase in online orders amid global lockdowns. Once lockdown restrictions loosened, this led to an “inventory bullwhip effect” as companies over-purchased merchandise to avoid future inventory shortages. Sustained supply-chain bottlenecks led retailers to continue over-purchasing—shifting from “just-in-time” inventory management to a “just-in-case” model in an effort to keep more inventory onsite. As a result, the demand for warehouse space skyrocketed.
The impact of this rising demand is significant. On one hand, warehouse sellers can get a significant premium for their property if they pursue a sale-leaseback of their real estate. However, companies looking to acquire or rent warehouse space might have a difficult time as vacancies are at record lows—for U.S. industrial properties it’s just 4.1%. Supply chain disruptions causing delays in construction materials also increase the build time for new warehouses, meaning many companies are left waiting several years for the space they need to accommodate today’s surging retail inventories.
From an investor perspective, rising demand often translates to low cap rates for well-located warehouses despite inflationary pressures and rising interest rates. However, the shortage in available space also enhances the criticality of these properties to tenants, making them less likely to vacate at the end of the lease term.
Re-shoring supply chains
Supply chain disruptions highlighted the risk of off-shore operations for many manufacturers. As a result, many manufacturers are making the decision to re-shore their production facilities to protect against such disruptions in the future. In fact, in 2021, a record 1,800 companies re-shored their production operations in the U.S.
Companies looking to re-shore production are choosing locations with a high availability of land for development, a large pool of skilled labor and well-developed transportation infrastructure including railways and ports. This has led to an increase in development in the Midwest and South due to both regions’ access to rail infrastructure and seaports respectively.
While re-shoring has contributed to the rising demand for warehouse space, it has also opened up new opportunities for investors as companies look to rent existing warehouses in tertiary markets that may not have historically been attractive, but have access to transportation infrastructure and land available for development.
Increased interest in last-mile logistics space
With limited warehouse space available, companies are having to get creative with their distribution strategies. One such method is through last-mile warehouses, which facilitate the movement of goods in the supply chain to the final destination. These warehouses are typically located close to the consumer and therefore decrease supply-chain costs while minimizing delivery time. As a result, warehouses situated near major highways and bridges that lead into metropolitan hubs are becoming highly in-demand for companies looking to make their distribution network more nimble. This presents an opportunity for investors who own these types of facilities to capitalize on demand and secure high-quality tenants on long-term leases.
Related Topics:
You May Also Like:

Sale-leaseback vs. Traditional Debt: A Company’s Guide to Evaluating the Options
For companies seeking capital to fund growth, finance an acquisition, reduce leverage or pursue other strategic priorities, traditional debt financing is often the first option considered. But companies that own significant real estate may have another source of capital available: a sale-leaseback. In a sale-leaseback, a company sells its real estate to an investor and simultaneously enters into a long-term lease, allowing it to continue operating at the property while unlocking capital otherwise tied up in a fixed asset. Unlike traditional corporate debt, a sale-leaseback does not add another loan that ultimately needs to be repaid. Instead, it converts owned real estate into liquidity while creating a long-term lease obligation. Neither approach is inherently better. The right choice depends on a company’s capital needs, strategic objectives, balance sheet priorities and long-term plans for its real estate. For companies evaluating the options, it is important to look beyond the headline cost of capital and consider the broader implications of each. Here are five factors to consider. 1. How much capital does the business need? A fundamental question is whether the financing approach can generate enough capital to accomplish the company’s objectives. Traditional debt can provide an efficient source of liquidity, but the amount a company can prudently borrow may be influenced by its existing leverage, credit profile and broader capital structure. For companies with substantial value tied up in owned real estate, a sale-leaseback provides another potential source of capital. By selling the property, the company can monetize the value of the asset and redeploy the proceeds elsewhere in the business. Those proceeds can be used for a range of strategic purposes, including funding growth initiatives, new acquisitions or reducing debt. The analysis therefore extends beyond the relative cost of capital and should focus on the company’s overall capital needs and which structure best aligns with its objectives. 2. What is the highest and best use of the company’s capital? Owning real estate can serve a business well, particularly when ownership is an important part of its long-term strategy. But it also means that capital remains invested in buildings rather than being deployed elsewhere in the company. That creates an opportunity-cost question: Could the capital currently invested in real estate generate greater strategic or financial value somewhere else? For example, a company may determine that investing in new equipment, expanding production, completing an acquisition, entering a new market or reducing existing debt better supports its strategic priorities than continuing to own its facilities. The key is to assess real estate ownership in the context of the company’s broader capital priorities. If capital invested in owned facilities could generate greater value elsewhere in the business, a sale-leaseback may be worth considering as part of the overall financing strategy. If ownership itself provides strategic value, retaining the property while raising capital through traditional debt may make more sense. 3. How does each option affect the company’s balance sheet? Financing decisions cannot be evaluated in isolation from a company’s overall capital structure. Traditional borrowing introduces additional debt and associated interest and repayment obligations. A sale-leaseback, by contrast, monetizes an existing asset and introduces a long-term lease obligation. The resulting accounting, tax and credit implications will depend on the business and the specific transaction, so companies should evaluate each structure with their accounting, tax and legal teams. Strategically, however, the distinction is important. A company looking to preserve debt capacity or reduce existing borrowings may evaluate a sale-leaseback differently from a company comfortable adding incremental leverage. The key is determining how each source of capital fits into the company’s broader financial strategy, rather than evaluating the transaction on its own. 4. What does the company’s long-term strategy look like? The appropriate financing structure also depends on where the business expects to be several years from now. A company taking on traditional debt should consider its ability to repay or refinance those obligations alongside its other capital needs. A company considering a sale-leaseback needs to think differently. Because it will enter into a lease, management should have conviction that the facility will continue to support the business's operations over that period. That makes the expected future role of the property an important part of the decision. A mission-critical facility that a company expects to occupy over the long term may be well suited to a sale-leaseback. A property that could become unnecessary as the company’s footprint changes may warrant a different strategy. 5. What flexibility will the company need in the future? Companies evolve. Production capacity changes, operations expand, facilities require modernization and sustainability investments become necessary. When weighing a sale-leaseback against traditional debt financing, companies should consider the flexibility each provides as the business evolves. A sale-leaseback can offer a different type of flexibility by pairing access to capital with a long-term real estate partner that may be able to support future property needs. W. P. Carey’s Carey Tenant Solutions platform, for example, is designed to support tenants beyond the initial acquisition through follow-on investments, including build-to-suits and expansions, redevelopment and renovations, and energy solutions. That makes the selection of a buyer-landlord an important component of the sale-leaseback decision. Just as companies consider the terms, capacity and flexibility of a lending relationship when evaluating traditional debt, they should assess whether a prospective real estate partner can support their longer-term needs. The economics at closing matter, but so does the ability of the partner to accommodate the business as it grows and changes. Looking beyond the cost of capital The decision between a sale-leaseback and traditional debt financing is ultimately bigger than the cost of one source of capital versus another. It is a decision about capital allocation. Companies should consider the amount of capital the business needs, its existing capital structure, the strategic importance of owning its real estate and how effectively newly available capital can be deployed. Interested in exploring whether a sale-leaseback could complement your broader capital strategy? Contact W. P. Carey to learn more.

Where Opportunity Exists in European Real Estate Today
As the European real estate industry gathers in Munich for EXPO REAL, investors are navigating a market defined by both uncertainty and evolving opportunities. While sentiment remains cautious amid ongoing economic and geopolitical challenges, opportunities continue to emerge for investors with disciplined underwriting and a long-term perspective. Here are four key themes we expect to shape conversations at this year's conference. Economic challenges persist in Germany, but defense spending could create new opportunities Compared with last year’s conference, the mood in Germany is likely to be more subdued. Europe's largest economy continues to face a range of challenges, including weaker industrial activity, geopolitical uncertainty and lingering concerns around inflation and interest rates. At the same time, increased defense spending across Germany and Europe could create an important counterbalance to some of these challenges. As governments commit more capital to defense, security and strategic manufacturing capabilities, demand for specialized industrial facilities and production infrastructure could increase. This investment has the potential to support certain manufacturing sectors, create new occupier demand and generate opportunities for real estate investors. Macroeconomic conditions will remain the dominant investment driver Macroeconomic conditions will continue to play a central role in real estate investment decisions across Europe over the next 12 to 18 months. While many investors had anticipated a more accommodative financing environment, recent rate hikes by the European Central Bank and the rise in long-term interest rates have added a new layer of complexity to the market. As a result, real estate investors remain focused on how financing costs, capital availability and geopolitical developments could influence property values and transaction activity across Europe. Periods of uncertainty can create selective opportunities, but disciplined underwriting and a long-term outlook remain critical for investors when evaluating new investments. Sale-leaseback activity will continue to grow Despite broader market uncertainty, the outlook for the European sale-leaseback market remains positive. As companies look for ways to strengthen balance sheets, improve liquidity and fund strategic initiatives, sale-leasebacks continue to offer a compelling source of capital. Private equity sponsors are similarly exploring sale-leasebacks as a tool to unlock value, support acquisition financing and optimize capital structures. While a significant inflationary or interest-rate shock could have a short-term impact, the broader trend points toward increased activity. As financing costs remain elevated and capital efficiency becomes more important for companies, sale-leasebacks are expected to remain a valuable financing solution across a variety of sectors. AI is reshaping real estate, but key questions remain Artificial intelligence continues to drive enormous interest in data centers and digital infrastructure. However, alongside the enthusiasm, important questions remain. Energy availability is emerging as one of the sector's biggest constraints. Across many European markets, power capacity is becoming increasingly difficult to secure, creating a bottleneck for future development. At the same time, investors are still evaluating how these assets should be valued over the long term. Rapid technological evolution, equipment depreciation and uncertainty around residual asset values create questions that have yet to be fully answered by the market. This may place a premium on assets and markets with reliable access to power and infrastructure capable of supporting future demand. Looking ahead Success in the current landscape will not be defined by predicting the next market shift, but by identifying opportunities that can withstand it. In an environment marked by uncertainty, investors focused on high-quality tenants, mission-critical real estate and creative capital solutions such as sale-leasebacks will be well positioned to take advantage of emerging opportunities.

How E-Commerce Is Shaping Supply Chains and Driving Demand for Logistics Real Estate
While the pandemic-era surge in online shopping has moderated, e-commerce remains one of the most powerful forces influencing logistics real estate. Consumer purchasing habits have fundamentally changed, with digital channels now firmly embedded in how people shop. As retailers, manufacturers and logistics providers adapt to rising expectations for speed, convenience and flexibility, the need for modern fulfillment infrastructure continues to expand. The result is a logistics landscape that is becoming increasingly sophisticated, with occupiers reevaluating distribution networks to better serve a digital-first economy. Logistics Has Become Critical to the E-Commerce Experience E-commerce has matured from a fast-growing retail channel into a foundational component of global commerce. According to a recent McKinsey survey, 57% of consumers rank digital as their primary purchasing channel—almost double the level reported in 2022. For retailers, this shift has significant supply chain implications. Fulfillment networks are being redesigned to support broader product assortments, deeper inventory levels, direct-to-consumer shipping, returns processing, and value-added services such as product assembly and customization. Real estate strategy is also becoming more closely tied to service levels. Facilities positioned near major population centers can help shorten delivery windows and improve the efficiency of last-mile logistics—the final stage of the delivery process, when goods move from a distribution facility to the end customer. As consumers continue to expect faster, more reliable delivery, this part of the supply chain has become a key competitive differentiator. Nearshoring Is Providing an Additional Tailwind Companies are increasingly pursuing nearshoring and onshoring initiatives to improve supply chain resilience, reduce transportation costs and bring production closer to end markets. These strategies gained momentum following years of supply chain disruptions and continue to be influenced by evolving trade policies and geopolitical considerations. Unlike last-mile strategies, which focus on the final movement of goods, nearshoring is reshaping the upstream side of the supply chain. By moving production closer to end markets, companies can improve operational control, reduce exposure to disruption and better align inventory with customer demand. In the U.S., changes in foreign trade policies and tariff structures have further encouraged companies to diversify sourcing strategies and establish a stronger domestic presence. Cross-border e-commerce companies, in particular, are expanding their U.S. logistics footprints to help future-proof operations amid potential regulatory changes. As new manufacturing facilities come online, the need for supporting warehouse, distribution and transportation infrastructure is expected to increase, creating additional opportunities within industrial and logistics real estate. A New Era for Logistics Real Estate It’s projected that U.S. e-commerce penetration—the percentage of total retail sales that occurs online—will rise from approximately 24% in 2025 to 30% by 2030. This growth has meaningful implications for logistics real estate demand, as every one percentage-point increase in e-commerce's share of retail sales translates into approximately 50 million to 70 million square feet of industrial space absorption. Beyond sheer volume growth, e-commerce is also changing the type of industrial and logistics space occupiers require. To support greater supply chain flexibility, companies are increasingly seeking modern facilities with higher clear heights, advanced automation capabilities and strong transportation connectivity. Looking Ahead E-commerce is no longer just changing how consumers shop—it is reshaping how companies build, operate and future-proof their supply chains. Well-located, modern facilities with the flexibility to support evolving distribution strategies are likely to remain in high demand, underscoring the long-term value of logistics assets in a digital-first economy.